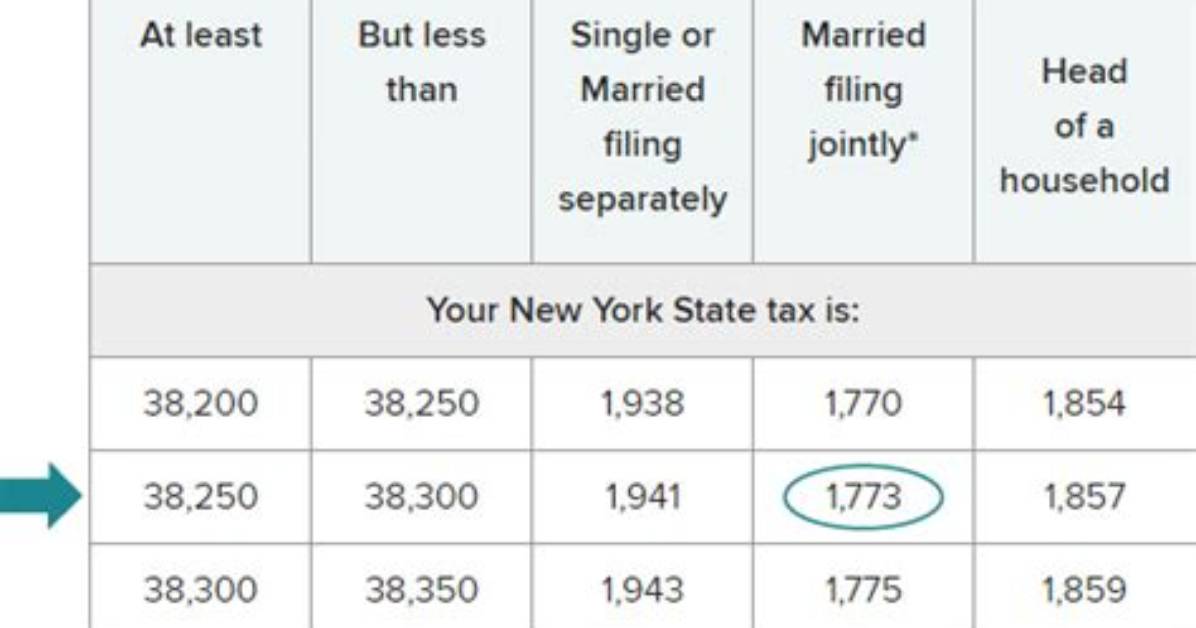
The number of allowances you claim on your W-4 form determines how much federal income tax is withheld from your paycheck. The more allowances you claim, the less tax is withheld
- Calculate your allowances: You can use the IRS withholding calculator or consult with a tax professional to determine the correct number of allowances to claim.
- Factors to consider: When determining the number of allowances to claim, consider factors such as your filing status, dependents, other income, and tax credits.
- Avoid underpaying: Claiming too few allowances can result in owing taxes when you file your return.
- Avoid overpaying: Claiming too many allowances can result in getting a refund, but you'll also have given the government an interest-free loan.
Claiming the correct number of allowances can help you avoid owing taxes when you file your return or getting a large refund. If you are unsure how many allowances to claim, consult with a tax professional.
Personal details and bio data
Calculate your allowances
Knowing how to calculate your allowances is essential for accurately determining the correct number to claim on your W-4 form, which directly impacts the amount of federal income tax withheld from your paycheck.
- IRS Withholding Calculator: The IRS provides a user-friendly online calculator that guides you through a series of questions to estimate your allowances based on your income, filing status, and other factors.
- Tax Professional Consultation: A tax professional can provide personalized advice tailored to your specific financial situation, ensuring that you claim the optimal number of allowances to minimize tax liability and avoid penalties.
- Factors to Consider: When calculating your allowances, consider factors such as your filing status (single, married, etc.), the number of dependents you claim, any additional income sources, and eligible tax credits.
- Accuracy and Adjustments: Regularly review and adjust your allowances as your financial circumstances change, such as a change in income, marital status, or the number of dependents, to ensure continued accuracy.
By understanding how to calculate your allowances and leveraging the available resources, you can effectively manage your tax withholding, avoid underpayment penalties, and maximize your refund or minimize your tax liability.
Factors to consider
Understanding the factors that influence the number of allowances you should claim on your W-4 form is essential for accurate tax withholding and effective financial planning.
- Filing Status: Your filing status, such as single, married, or head of household, determines the standard deduction and tax rates you are eligible for. This directly impacts the number of allowances you can claim.
- Dependents: Each dependent you claim on your tax return entitles you to an additional allowance. This reduces your taxable income and, consequently, the amount of tax withheld from your paycheck.
- Other Income: If you have income from sources other than your primary job, such as self-employment or investments, this additional income may necessitate claiming more allowances to avoid overpaying taxes.
- Tax Credits: Certain tax credits, such as the child tax credit or earned income tax credit, can also affect the number of allowances you should claim. These credits further reduce your tax liability, potentially warranting additional allowances.
By considering these factors and accurately determining the number of allowances to claim, you can optimize your tax withholding, minimize the risk of underpayment penalties, and potentially increase your refund or reduce your tax liability.
Avoid underpaying
Claiming too few allowances on your W-4 form can lead to underpaying your federal income taxes throughout the year. When you file your tax return, you may discover that you owe a significant amount to the IRS, potentially resulting in penalties and interest charges.
To avoid this scenario, it's crucial to accurately determine the correct number of allowances to claim based on your personal and financial circumstances. Factors such as your filing status, dependents, other income sources, and eligible tax credits should all be considered when making this calculation.
Understanding the connection between claiming too few allowances and potentially owing taxes is essential for responsible financial planning. By ensuring that you claim the appropriate number of allowances, you can minimize the risk of underpayment, avoid penalties, and prevent unexpected tax burdens at the end of the tax year.
Avoid overpaying
Understanding the implications of claiming too many allowances on your W-4 form is crucial in relation to determining "how many allowances should I claim NYC." Claiming too many allowances reduces the amount of federal income tax withheld from your paycheck, potentially resulting in a larger refund when you file your tax return.
- Impact on Withholding: Claiming too many allowances reduces the amount of tax withheld from each paycheck, leading to a lower net income. While this may seem beneficial, it can result in a smaller refund or even a tax liability when you file your return.
- Refund vs. Loan: While receiving a larger refund may be appealing, it essentially means you have overpaid your taxes throughout the year, giving the government an interest-free loan. The refund represents the excess amount withheld, which could have been used for savings, investments, or other financial goals.
- Tax Liability and Penalties: If the amount of tax withheld is significantly less than what you owe, you may face a tax liability when you file your return. This can result in penalties and interest charges, negating any benefit from claiming too many allowances.
- Accuracy and Adjustments: Determining the correct number of allowances to claim requires careful consideration of your personal circumstances. Regularly reviewing and adjusting your allowances as your financial situation changes ensures accurate withholding and minimizes the risk of overpaying or underpaying taxes.
In summary, avoiding overpaying taxes by claiming too many allowances is essential for responsible financial planning. It ensures you retain more of your hard-earned income throughout the year, reduces the risk of tax liabilities and penalties, and prevents the government from receiving an unnecessary interest-free loan.

